The Real Cost of Buying an HDB Flat
Buying an HDB flat costs more than the price tag: a 25% downpayment, Buyer's Stamp Duty, legal, survey and registration fees, and any cash-over-valuation — then insurance, property tax and conservancy charges once you move in.
On this page12 sections · tap to jump
- 01The costs, grouped
- 021. Downpayment and the 75% loan limit
- 032. Buyer’s Stamp Duty (BSD)
- 043. Legal, registration and survey fees
- 054. Application, option and valuation fees
- 065. Cash-over-valuation (COV)
- 076. Insurance: fire insurance and HPS
- 087. After you move in: property tax, S&CC, utilities
- 098. What lowers the cost: grants and CPF
- 10A worked example
- 11BTO vs resale on costs
- 12FAQ
The sticker price of an HDB flat is only the start. On top of it sit a downpayment, stamp duty, a handful of legal and administrative fees, possibly a cash-over-valuation, and recurring costs that begin the day you collect the keys. This guide lays out each one with the official figures, so you can budget for the real total rather than the headline number. It covers a resale purchase; where a new (BTO) flat differs, we say so.
The costs, grouped
The money falls into three buckets: what you must fund upfront (downpayment and cash fees), the one-off transaction fees (stamp duty, legal, survey, registration), and the recurring costs after you move in (insurance, property tax, conservancy charges). The step-by-step buying process explains when each is paid; this page explains how much.
1. Downpayment and the 75% loan limit
Your loan is capped by the Loan-to-Value (LTV) limit — the most you can borrow as a share of the lower of price or valuation. With effect from 20 August 2024, the LTV limit for HDB concessionary loans was lowered from 80% to 75%, matching the limit for bank loans. That means you fund at least 25% of the price yourself.
How that 25% is paid differs by loan type:
- HDB concessionary loan: the 25% downpayment can be paid entirely from CPF Ordinary Account savings — there is no minimum cash requirement.
- Bank loan: of the 25%, at least 5% must be in cash and the remaining 20% can be cash or CPF.
The LTV figure is a maximum, not a target; borrowing less lowers your monthly repayment. The HDB loan interest rate is 2.60% per annum for the quarter 1 October to 31 December 2026, pegged at 0.1 percentage point above the CPF Ordinary Account rate and reviewed every quarter. Weigh the two routes in HDB loan vs bank loan.
2. Buyer’s Stamp Duty (BSD)
Every buyer pays Buyer’s Stamp Duty, calculated on the price or market value, whichever is higher. The residential rates (since 15 February 2023) are tiered:
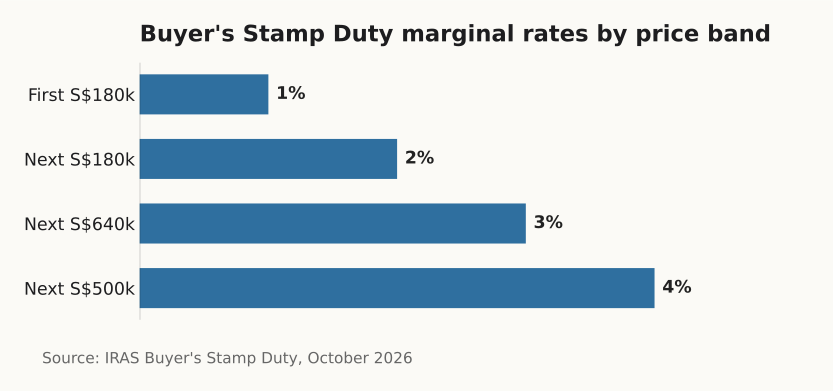
Residential BSD rates applied band by band (higher bands reach 5% and 6%).
| Price band | BSD rate |
|---|---|
| First S$180,000 | 1% |
| Next S$180,000 | 2% |
| Next S$640,000 | 3% |
| Next S$500,000 | 4% |
| Next S$1,500,000 | 5% |
| Remaining amount | 6% |
For a S$700,000 four-room resale flat, BSD works out to S$1,800 + S$3,600 + S$10,200 = S$15,600. BSD is normally paid from CPF; you can ask to pay in cash instead. Estimate your own figure with the Buyer’s Stamp Duty calculator.
Additional Buyer’s Stamp Duty (ABSD) is separate. A Singapore citizen buying their first residential property pays no ABSD. It applies to a citizen’s second property (20%) and above, to Singapore permanent residents (5% on a first property) and to foreigners — so most first-time HDB buyers pay none.
3. Legal, registration and survey fees
If you appoint HDB to act for you in the purchase and mortgage, its conveyancing fee for a resale transfer is set by the Housing and Development (Conveyancing Fees) Rules: 13.5 cents per S$100 on the first S$30,000, 10.8 cents on the next S$30,000, and 9 cents thereafter, with a minimum of S$21.80 (including GST). On a S$700,000 flat that is roughly S$660 before the mortgage portion. A private solicitor typically charges more; the choice is yours.
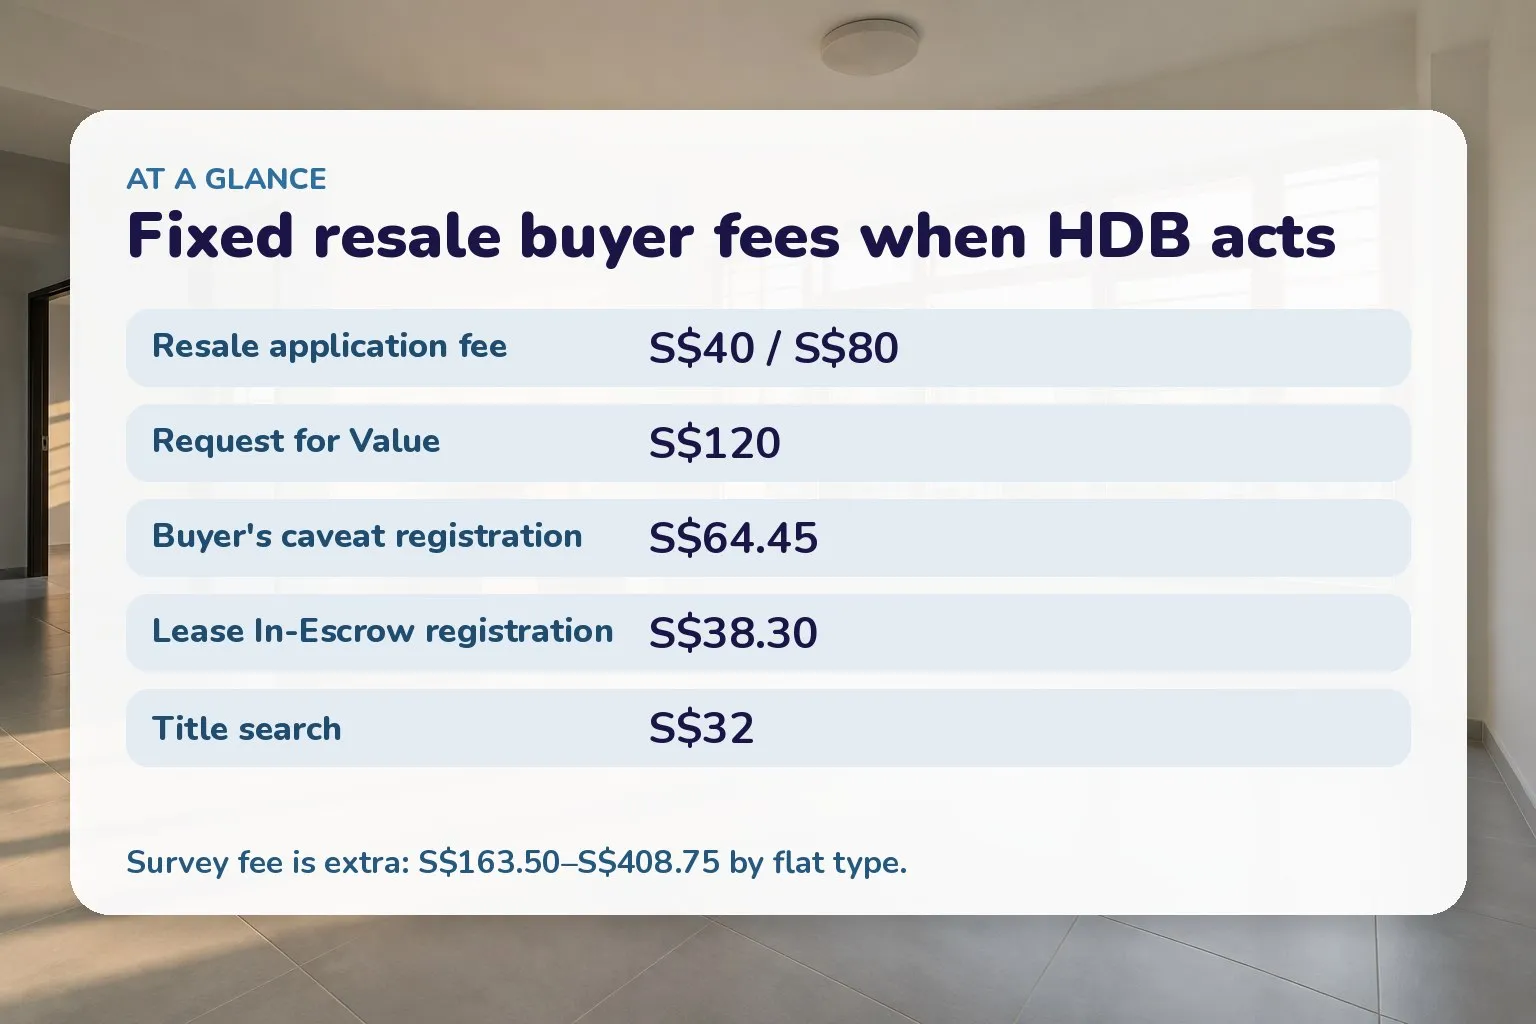
Fixed charges for a resale purchase when HDB acts for you.
Alongside the legal fee come several fixed charges when HDB acts:
- Caveat registration (buyer’s caveat): S$64.45, plus S$64.45 for a mortgagee’s caveat if you take an HDB loan.
- Lease In-Escrow registration: S$38.30.
- Title search: S$32.
- Survey fee by flat type: S$163.50 (2-room Flexi), S$231.60 (3-room), S$299.75 (4-room), S$354.25 (5-room), S$408.75 (Executive).
4. Application, option and valuation fees
Three small fees bookend the deal:
- Resale application fee: S$40 for 1- and 2-room flats, S$80 for 3-room and larger, paid by each party and non-refundable. (A BTO application costs just S$10.)
- Option fee: paid to the seller when you receive the Option to Purchase — between S$1 and S$1,000 — with an option exercise fee later so that the two together do not exceed S$5,000. These form part of the resale price.
- Request for Value fee: S$120, due by the next working day after the Option Date if you are financing with CPF or a loan.
5. Cash-over-valuation (COV)
HDB values the flat after you submit the Request for Value. Where the agreed price exceeds HDB’s valuation, the difference is cash-over-valuation, and it must be paid in cash — CPF and your loan cannot cover it, because both are capped at the valuation. There is no fixed COV figure; it depends entirely on the deal you negotiate, so check recent transacted prices before you agree a price.
6. Insurance: fire insurance and HPS
HDB Fire Insurance is mandatory for as long as you have an outstanding HDB loan. It is remarkably cheap: the five-year premium (for policies from 16 August 2024 to 15 August 2029) ranges from S$1.11 to S$6.68 depending on flat size — for example S$3.27 for a 3-room and S$4.59 for a 4-room flat. It covers only the building structure HDB originally built, not your renovations or belongings, so many owners add a separate home contents policy.
The Home Protection Scheme (HPS) is a mortgage-reducing insurance that is compulsory for members who use CPF to service their monthly HDB loan instalment; the premium is deducted from CPF.
7. After you move in: property tax, S&CC, utilities
Ownership brings recurring bills:
- Property tax, charged on the flat’s Annual Value (its estimated annual rent), at owner-occupier rates from 1 January 2025: 0% on the first S$12,000 of AV, 4% on the next S$28,000, 6% on the next S$10,000, rising progressively. Most flats fall in the lowest bands, and a one-off 15% property tax rebate for owner-occupied HDB flats applies in 2026.
- Service & Conservancy Charges (S&CC): roughly S$21 to S$123 a month depending on flat size, for a Singaporean owner-occupier.
- Utilities, maintenance and renovation: renovation and furniture are real costs but have no official figure — budget for them separately rather than treating them as fixed.
8. What lowers the cost: grants and CPF
For first-timers, CPF housing grants can sharply cut the real outlay. The Enhanced CPF Housing Grant (EHG) reaches up to S$120,000 for eligible families (S$60,000 for singles) on both new and resale flats, and resale buyers may stack further grants. All grants are paid into your CPF Ordinary Account to offset the price, not handed over as cash. See who qualifies in CPF housing grants: eligibility and amounts. If you have taken a subsidised flat before, factor in the resale levy.
A worked example
BTO vs resale on costs
A BTO flat skips some resale-only costs: the application fee is S$10 (not S$40–S$80), there is no Request for Value fee or COV, and the option fee goes toward your downpayment. But BTO buyers wait years for completion and face a different grant mix. Compare the trade-offs in BTO vs resale, and size your overall budget with the affordability calculator.
FAQ
Can I pay stamp duty and fees with CPF? BSD and the HDB legal fees can be paid from CPF; the option fee, option exercise fee and any cash-over-valuation must be in cash.
Is the CPF I use really a “cost”? Not lost, but not free. CPF Ordinary Account savings you use to buy accrue 2.5% interest per year, and you must refund the principal plus that accrued interest to your CPF when you eventually sell the flat.
What is the single biggest cash item? Usually the cash portion of the downpayment (on a bank loan) or a cash-over-valuation, both of which CPF cannot cover.
Related
- HDB resale flat buying process: step by step
- CPF housing grants: eligibility and amounts
- HDB loan vs bank loan
- Selling your HDB flat: process and fees
General information to help you budget, not financial, tax or property advice. Confirm your exact figures with HDB, IRAS and CPF. We do not represent buyers or sellers.
Sources
- Buyer's Stamp Duty (BSD) — Inland Revenue Authority of Singapore (as of October 2026)
- Additional Buyer's Stamp Duty (ABSD) — Inland Revenue Authority of Singapore (as of October 2026)
- HDB option fee and housing expenses you should know — Central Provident Fund Board (as of April 2026)
- Housing and Development (Conveyancing Fees) Rules — Singapore Statutes Online (AGC) (as of May 2026)
- Measures to Cool the HDB Resale Market (LTV lowered to 75%, EHG increased) — Ministry of National Development / HDB (as of August 2024)
- Interest Rate for HDB Housing Loan — Housing & Development Board (as of October 2026)
- Property Tax on Residential Property — Government of Singapore (as of October 2026)
- HDB Fire Insurance (5-year premiums, 16 Aug 2024–15 Aug 2029) — Housing & Development Board (as of October 2026)