HDB Flat Eligibility (HFE) Letter Explained
An HDB Flat Eligibility (HFE) letter is HDB's consolidated check of whether you can buy a flat, receive CPF housing grants, and take an HDB loan. You need a valid one before buying, and it lasts nine months.
On this page11 sections · tap to jump
- 01What an HFE letter is
- 02When you need a valid HFE letter
- 03What the HFE letter assesses
- 04How to apply: the two steps
- 05How long approval takes
- 06What you need to provide
- 07Applying for a bank loan at the same time
- 08If your situation changes after issue
- 09If your HFE letter is expiring
- 10A quick checklist before you apply
- 11Frequently asked questions
The HDB Flat Eligibility (HFE) letter is HDB’s consolidated check of whether you can buy a flat, how much in CPF housing grants you may receive, and how large an HDB housing loan you can take. You must hold a valid HFE letter before you buy, and it lasts nine months from the date it is issued. This guide covers what the letter decides, when you need it, how to apply, and what happens if your situation or the calendar runs against you.
What an HFE letter is
The HFE letter “gives homebuyers a consolidated assessment of their housing and financing options”. In one application you learn upfront whether you are eligible to buy a new or resale HDB flat, to receive CPF housing grants and the grant amount, and to take an HDB housing loan and the loan amount. It replaced the older HDB Loan Eligibility (HLE) letter, which only assessed the loan — the HFE folds flat eligibility and grants into the same check.
That single outcome is what the rest of your flat hunt is built on. Once you have it, you can size a realistic budget, see which grants apply, and know the ceiling on what you can borrow before you commit to a particular flat.
When you need a valid HFE letter
You “must have a valid HFE letter before you can buy an HDB flat”. In practice the letter gates two different moments depending on how you buy:
- New flat (BTO, Sale of Balance Flats, open booking): you need a valid HFE letter before you can apply during the sales exercise.
- Resale flat: you need it before you can obtain an Option to Purchase (OTP) from the seller and before you submit the resale application to HDB.
Because a resale OTP cannot be granted to you without the letter, and a new-flat application cannot be made without it, the HFE letter is genuinely the first step of buying — not paperwork you catch up on later. Our step-by-step resale buying process shows where it sits in the wider timeline.
What the HFE letter assesses
The letter checks three things at once — your eligibility to buy, your grant entitlement, and your loan eligibility and amount. For an HDB housing loan, the conditions include that at least one applicant is a Singapore Citizen, a monthly household income ceiling of $16,000 for families and $8,000 for singles, and that no applicant has disposed of a private residential property in the last 30 months before the HFE application. These revised income ceilings apply to households who apply for an HFE letter from 24 August 2026.
The income ceiling is the same figure used for a new subsidised flat, a resale flat with a CPF Housing Grant, and the HDB loan — so one number governs much of your eligibility. For the detail on who counts in the household and how income is added up, see the HDB income ceiling guide and CPF housing grants eligibility.
How to apply: the two steps
Applying is a two-step process on the HDB Flat Portal, logging in with Singpass:
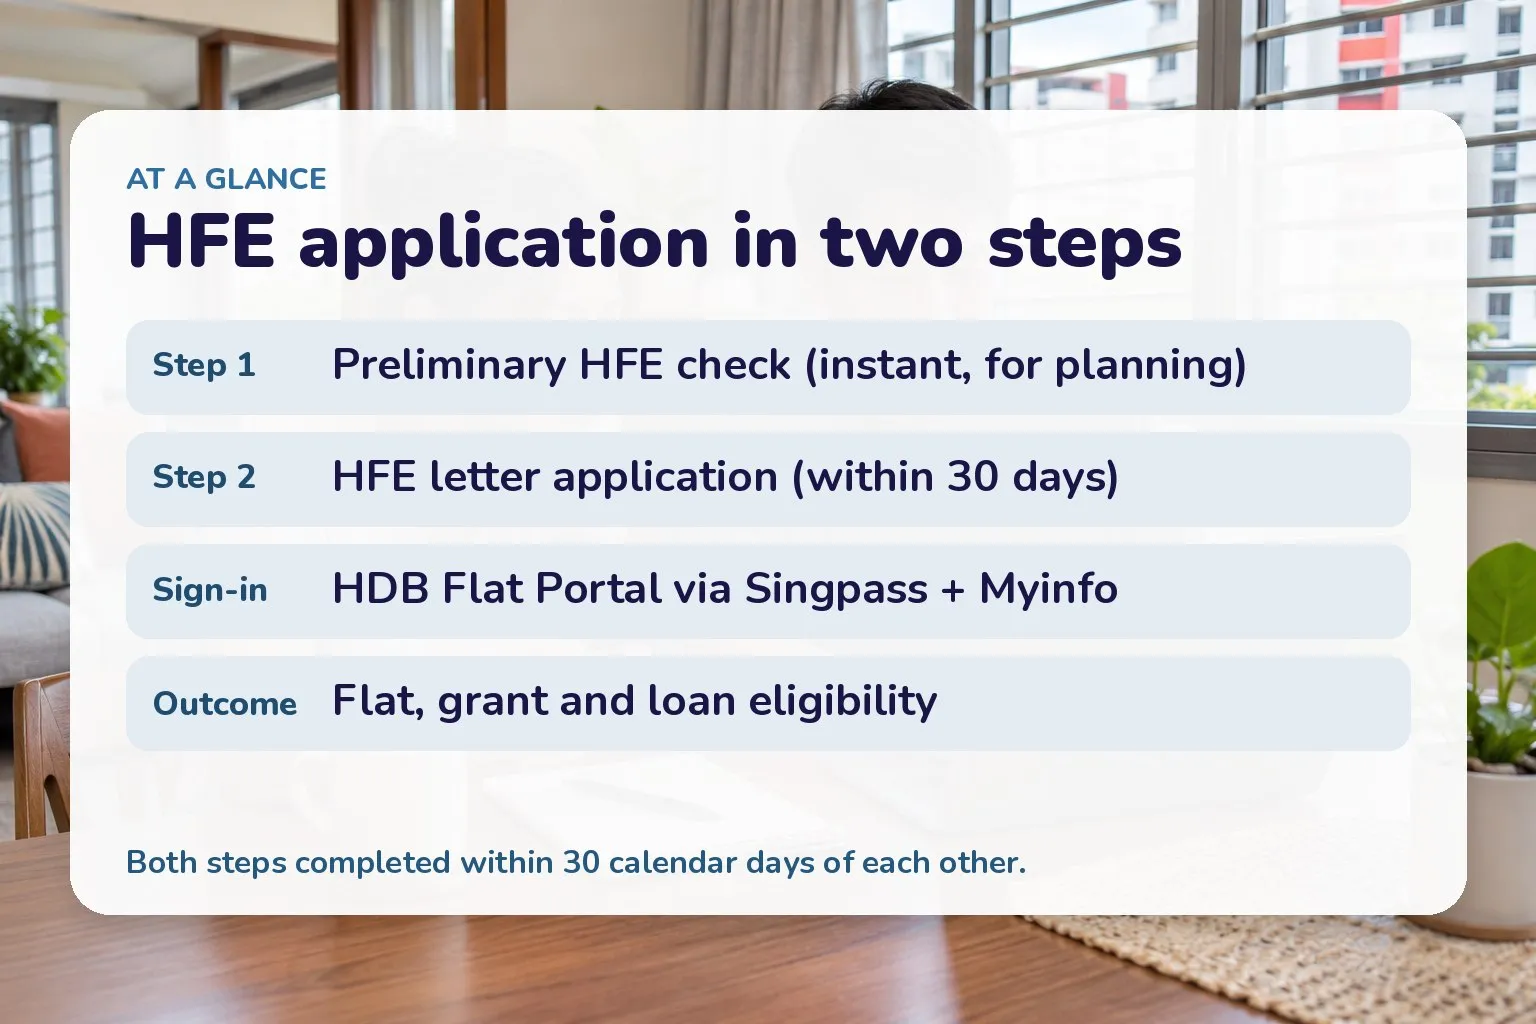
The two-step HFE process on the HDB Flat Portal. Source: HDB / MyNiceHome, November 2026.
- Preliminary HFE check. You provide household particulars (Myinfo can retrieve them), income details, declare any interest in private property, and state whether you intend to take a housing loan. On submission you get a preliminary assessment of your eligibility to buy, your grants and your loan — useful for planning, but not the letter itself.
- HFE letter application. You confirm your loan intent, can compare HDB and bank loan packages, provide further details and upload supporting documents, and all applicants and occupiers sign electronically with Singpass.
How long approval takes
It “typically takes about one month for an HFE letter application to be approved”, after all required documents are in. Processing can run longer during peak periods — the month before or during a sales launch — so apply early if a specific exercise is in view. HDB notifies you by SMS and email when the letter is ready, and you view it on the HDB Flat Portal.
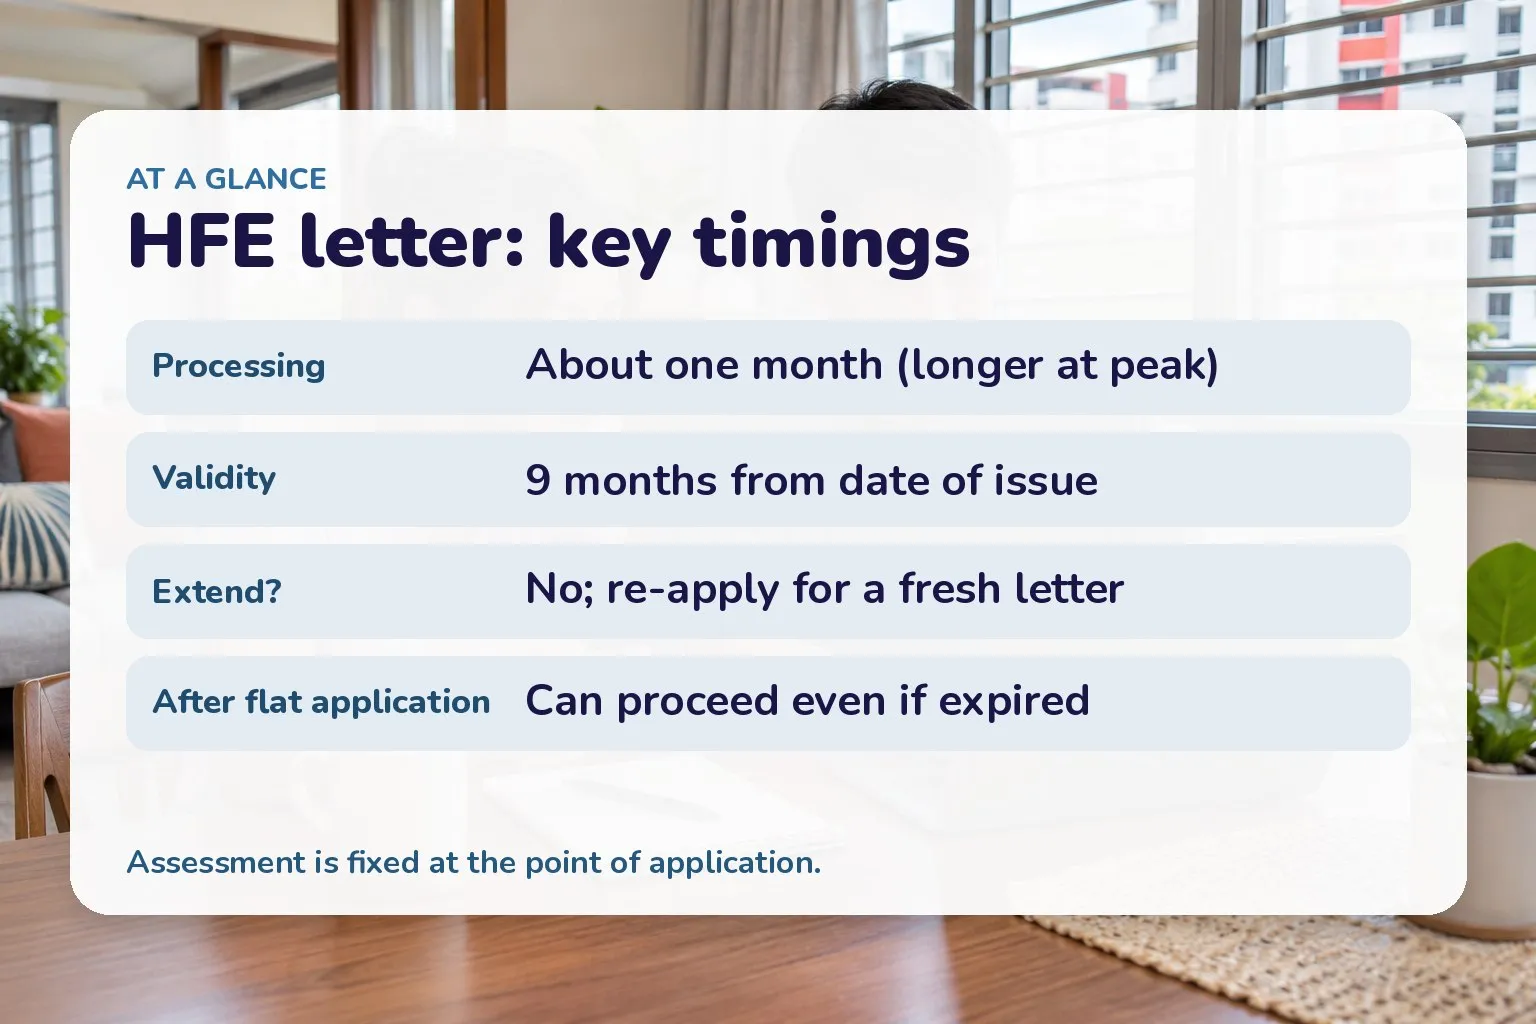
Timings for the HFE letter. Source: HDB / MyNiceHome, November 2026.
What you need to provide
Myinfo pulls most particulars, employment and your latest Notice of Assessment, but you may still be asked to upload documents. Files must be in PDF, JPG or PNG format, up to 5MB each and 40MB in total, and in English, Chinese, Malay or Tamil — otherwise attach an official English translation. If Myinfo does not hold a detail HDB needs, gather the document (for example from your employer) before you submit, because an incomplete set delays the assessment.
Applying for a bank loan at the same time
Inside the HFE letter application you can request an In-Principle Approval (IPA) from participating banks, so you line up your loan while HDB assesses your eligibility. The participating financial institutions on the portal’s integrated loan service are DBS, Hong Leong Finance, Maybank, OCBC and UOB. Each bank liaises with you directly on the IPA outcome. If you are weighing the HDB concessionary loan against a bank package, our HDB loan vs bank loan comparison sets out the trade-offs, and the affordability calculator helps you pressure-test the monthly repayment.
If your situation changes after issue
Your eligibility, grants and loan are “assessed at the point of the HFE letter application”. During the nine-month validity, the Enhanced CPF Housing Grant and loan amounts are not reviewed, even if your income rises afterwards. That cuts both ways:
- If your household income exceeds the ceiling after issue, you may still apply for a flat as long as the HFE letter remains valid.
- If you only now qualify for a higher grant (say you have since met a grant’s employment condition), the issued letter will not reflect it unless you cancel and apply for a fresh one.
If your HFE letter is expiring
An HFE letter is “valid for 9 months from the date of issue and HDB is unable to extend it”. If it is expiring within the next 30 days and you have not yet submitted a flat application, apply for a fresh letter. Where nothing has changed except employment or income, the first applicant can submit a re-application — and you can keep using the unexpired letter until the fresh one is issued. Importantly, if you have already used the letter to submit a flat application, you may proceed with the purchase even after it expires.
A quick checklist before you apply
- Settle who is in the household (applicants and occupiers) first.
- Have each person’s Singpass ready — everyone listed must sign.
- Check your income against the ceiling and your grant conditions in advance.
- Apply early if you are aiming at a specific BTO exercise or have found a resale flat.
- Decide whether you want an IPA from a bank at the same time.
Frequently asked questions
Is the preliminary HFE check the same as the HFE letter? No. The preliminary check gives an instant, non-binding assessment for planning. Only the second step — the HFE letter application — produces the letter you need to buy.
I am a single aged 35 and above. Can I compare applying alone versus with my parents? Yes. You can complete the preliminary check twice to see the outcomes as a Single and as a Family, then apply the way that suits you.
Does the HFE letter guarantee a flat or a grant amount? It confirms eligibility and the amounts at the point of application; it does not reserve a flat. Your grant and loan figures hold for the nine-month validity and are not revised upward during that time.
What if I don’t take an HDB loan? You still need the letter — it confirms your eligibility to buy and to receive grants even if you take a bank loan instead of an HDB loan.
Can I shorten the wait? Not really, but submitting a complete set of documents and avoiding peak sales-launch periods helps the roughly one-month processing run smoothly.
Related
- HDB loan vs bank loan: which is cheaper?
- Loan-to-value (LTV) limits explained
- HDB income ceiling: who qualifies
General information, not financial advice. Check HDB and CPF for the current rules and figures before you act.
Sources
- How to Apply for an HDB Flat Eligibility (HFE) Letter — HDB (MyNiceHome) (as of November 2026)
- HDB Flat Eligibility (HFE) letter - what to know — Central Provident Fund Board (as of November 2026)
- Outcome of HFE Letter Application (FAQ) — Housing & Development Board (as of November 2026)
- HFE Letter Application Process (FAQ) — Housing & Development Board (as of November 2026)
- Housing Loans for HDB Flat Buyers — HDB (MyNiceHome) (as of November 2026)
- Revised Income Ceilings for Citizen Families and Singles (Annex A) — Housing & Development Board (as of November 2026)