How Much Downpayment for an HDB Flat?
You fund at least 25% of an HDB flat's price as the downpayment, because the loan is capped at 75%. On an HDB loan it can come entirely from CPF; a bank loan needs at least 5% in cash.
The HDB downpayment is the slice of the flat price you pay from your own savings, because your housing loan covers only part of it. For most buyers that slice is at least 25% of the price — and how much of it has to be cash, and when you have to find it, depends on your loan type and on a scheme or two for younger buyers. This guide sets out the figures, the timing, and the ways to pay less upfront.
How much downpayment you need
Your loan is capped by the Loan-to-Value (LTV) limit, the most you can borrow as a share of the lower of the flat’s price or value. Since 20 August 2024 the limit for an HDB concessionary loan is 75%, matching bank loans, so you fund at least 25% of the price yourself. The Monetary Authority of Singapore sets the LTV, which “determines the maximum amount an individual can borrow from a financial institution (FI) for a housing loan”.
That 25% is a floor set by the loan cap, not a target — borrow less and your downpayment simply rises. Two things can lift the floor further: if your loan tenure is long or you are an older borrower, the limit drops to 55%, so the downpayment becomes 45%. Our loan-to-value limits guide works through exactly when that happens.
Cash versus CPF: what each loan type needs
The 25% is the same whichever loan you take, but the cash portion is not:
- HDB concessionary loan: the whole downpayment can be paid from your CPF Ordinary Account (OA) savings — there is no minimum cash requirement.
- Bank loan at the 75% limit: at least 5% of the price must be cash; the remaining 20% can be CPF OA or cash.
- Bank loan at the 55% limit: at least 10% must be cash.
CPF confirms your “OA savings can also be used for downpayment and housing loan taken for the property purchase, stamp and legal fees”. So for most first-time buyers, only a small cash slice — or none, on an HDB loan — has to come out of the bank account. What CPF can and cannot fund is covered in using CPF to buy a flat, and the two loan routes are weighed in HDB loan vs bank loan.
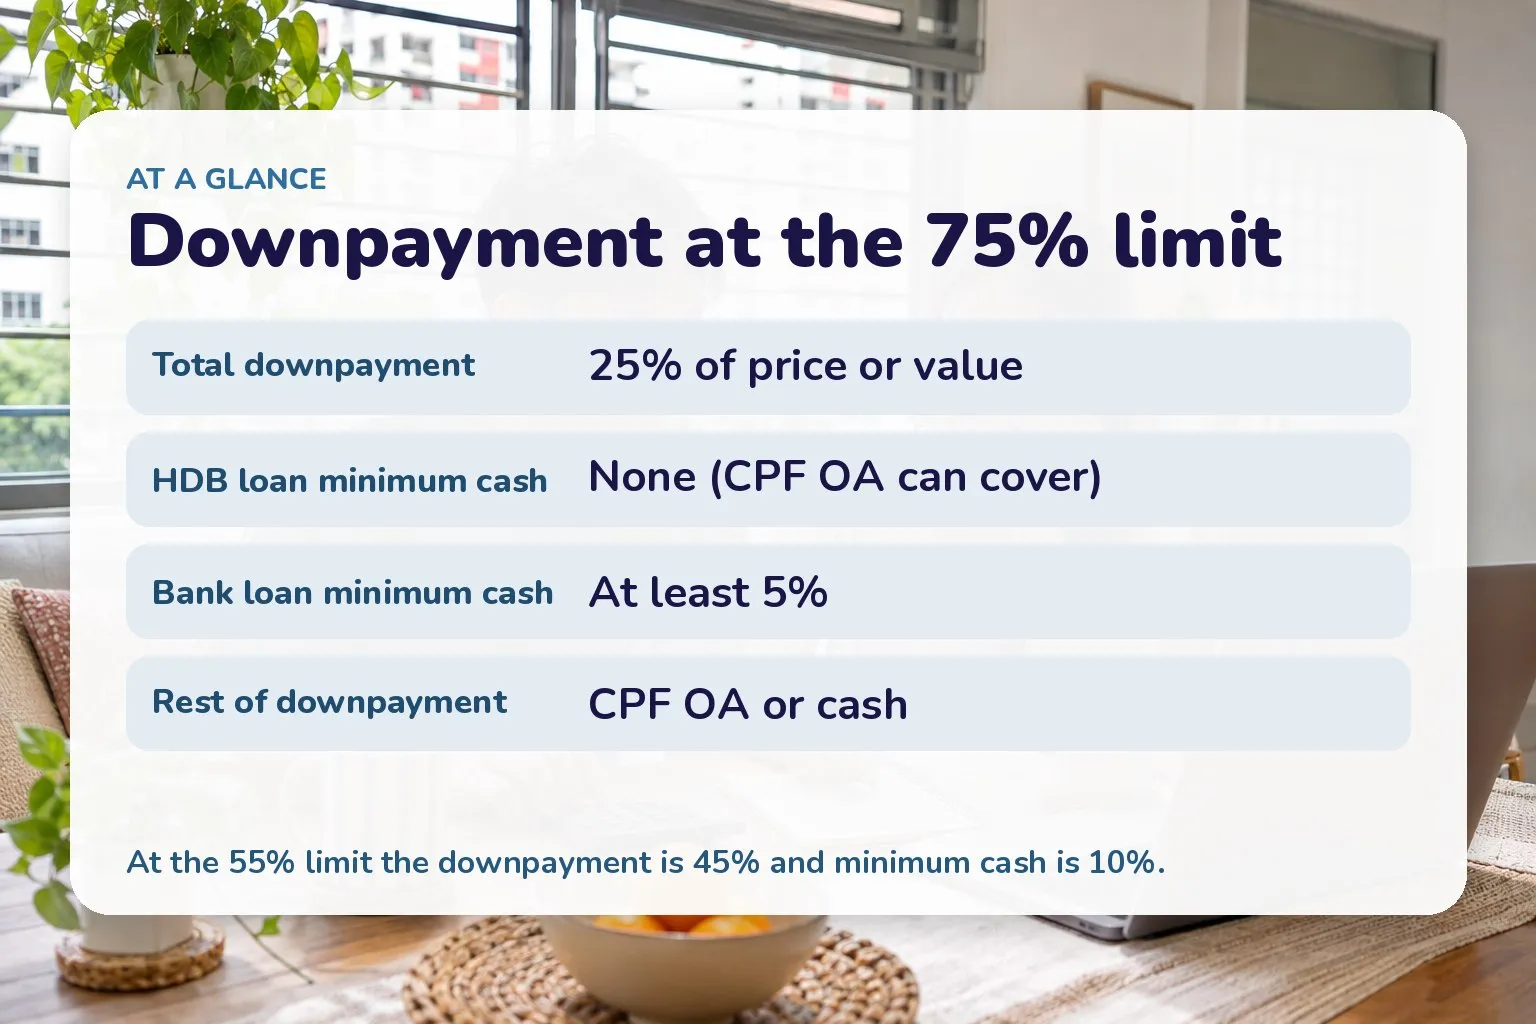
How the 25% downpayment splits between cash and CPF by loan type. Source: HDB / MAS, November 2026.
When each payment is due
For a new (BTO or SBF) flat the downpayment is not paid in one go. It falls in two stages, with years in between:
- At booking you pay the option fee — S$2,000 for a 4-room or bigger flat, S$1,000 for a 3-room and S$500 for a 2-room Flexi, in cash. This counts towards the flat price.
- When you sign the Agreement for Lease (within about nine months of booking) you pay the first part of the downpayment.
- At key collection, often three to four years after booking for a BTO flat, you pay the balance.
How that split works, without any scheme, is set by HDB:
| Loan type | At signing (AFL) | At key collection |
|---|---|---|
| HDB loan / no loan | 10% | 15% |
| Bank loan (75% LTV) | 20% (min 5% cash) | 5% |
| Bank loan (55% LTV) | 20% (min 10% cash) | 25% |
So on an HDB loan the 25% is halved neatly between the two stages; on a bank loan the bulk falls at signing. A resale flat works differently — see below.
Staggered Downpayment Scheme (SDS)
If finding 10% or 20% at signing is hard, the Staggered Downpayment Scheme lets eligible buyers “pay a lower downpayment when you sign the Agreement for Lease” and “pay the remaining downpayment when you collect your keys instead”. It does not reduce the total 25% — it shifts most of it to key collection, by which point you have had years to save.
Under the standard SDS the signing instalment is halved, so a buyer pays 5% (HDB loan) or 10% (bank loan) at signing instead of 10% or 20%, with the rest at keys:
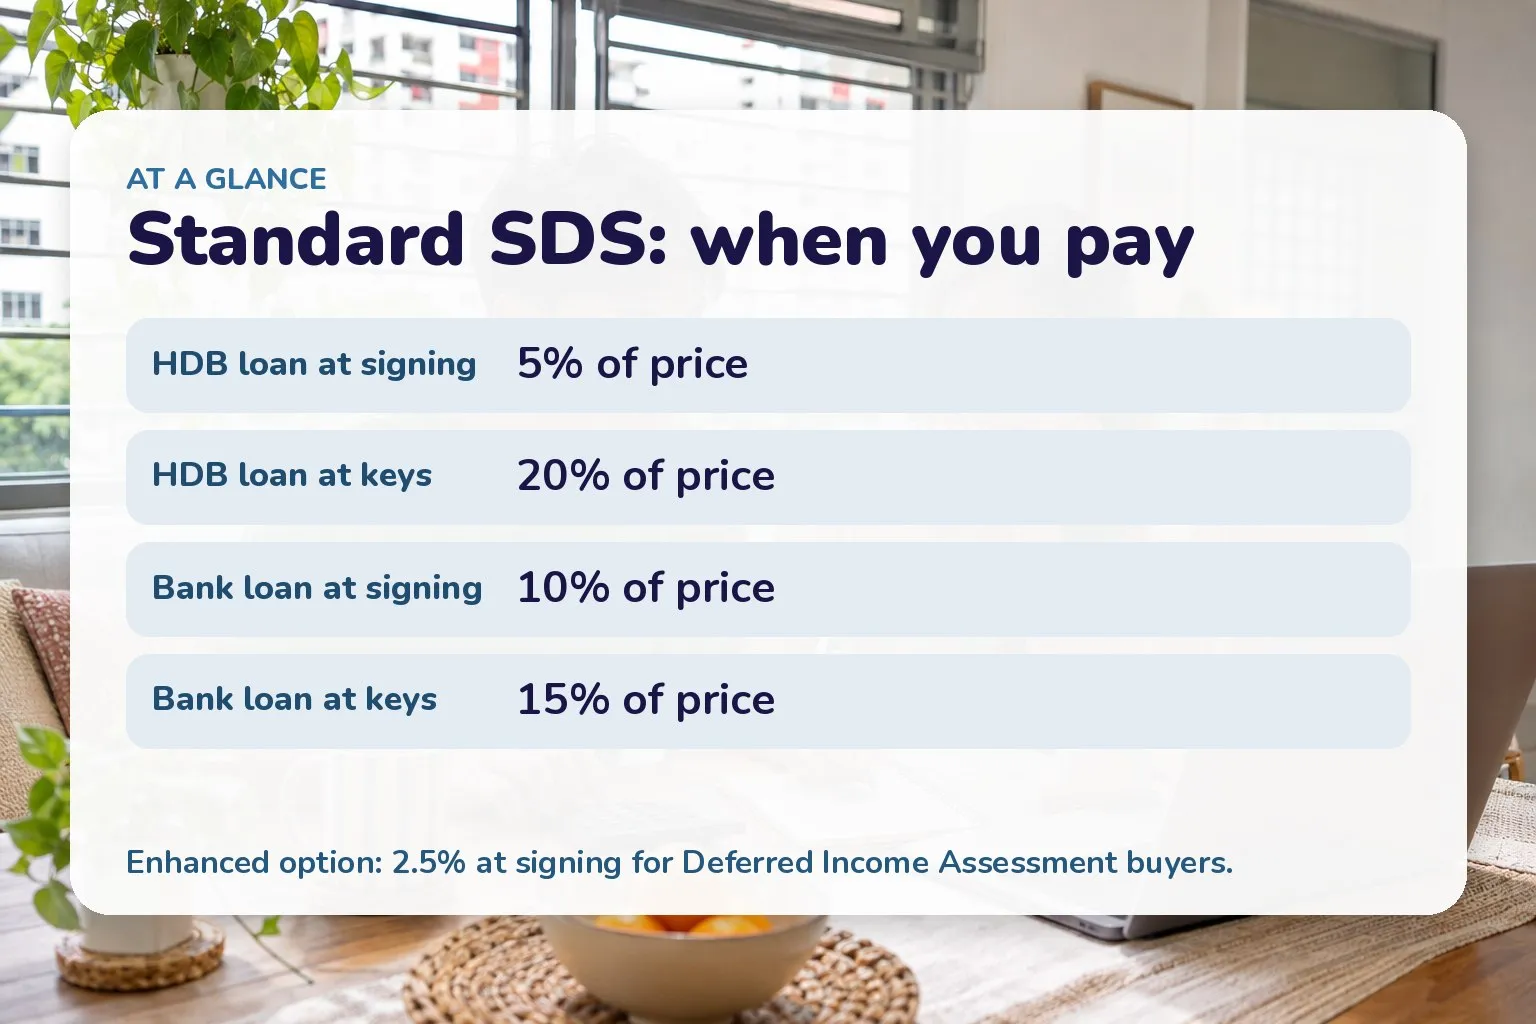
Downpayment timing under the standard SDS, by loan type. Source: HDB, November 2026.
The enhanced 2.5% option
Couples who also qualify for Deferred Income Assessment get an enhanced version: from the June 2024 sales exercise, HDB “will be enhanced for eligible applicants who book an uncompleted flat. They can pay a smaller proportion of the required downpayment, i.e. 2.5% of the flat price, when they sign the Agreement for Lease.” The balance — 22.5% on an HDB loan, or 42.5% at the 55% bank limit — is then due at key collection.
Deferred Income Assessment lets you “apply for a flat first, and be assessed for your eligibility to receive grants and an HDB housing loan later”, nearer key collection — useful if you are still studying, serving National Service, or newly working and your income will be higher by then.
Who qualifies for the SDS
You do not apply for either scheme: “If you fulfil the eligibility conditions, HDB will inform you when you book a flat.” For couples, the SDS conditions are:
- Both of you are first-timers, or one is a first-timer and the other a second-timer;
- You applied for an HFE letter on or before the younger applicant’s 30th birthday;
- You booked an uncompleted 5-room or smaller flat.
Right-sizers who have not yet sold their existing flat and book an uncompleted 3-room or smaller flat can also qualify. Deferred Income Assessment has its own test: both of you a full-time student or National Serviceman (or finished within the last 12 months), at least one applicant aged 30 or below, married or applying under the Fiancé/Fiancée Scheme, and at least one a first-timer. Both schemes require an HFE letter before booking.
Resale flats: one downpayment, not two
A resale flat has no staggered schedule. You pay a small option fee (S$1 to S$1,000) when you receive the Option to Purchase, then an option exercise fee so the two together do not exceed S$5,000, and the remaining downpayment at completion a few weeks later. Because the keys come almost immediately, there is no multi-year gap to spread the payment across, and the SDS does not apply. The full resale cost, including stamp duty and fees, is in the real cost of buying an HDB flat, and the sequence of steps in the resale buying process.
A worked example
Any CPF housing grant you receive lands in your CPF OA and can offset the price, easing the downpayment too. To size your own numbers, use the affordability calculator.
Frequently asked questions
Can CPF cover the entire downpayment? On an HDB loan, yes — there is no minimum cash. On a bank loan at least 5% of the price must be cash (10% at the 55% limit); the rest can be CPF OA.
Is the downpayment 20% or 25%? 25%. The old 20% applied when the HDB loan limit was 80%; it was lowered to 75% on 20 August 2024, so the minimum downpayment is now 25%.
Does the option fee come on top of the downpayment? No — the option fee counts towards the flat price. But it must be paid in cash at booking, so budget for it separately from your CPF downpayment.
What if I take no housing loan at all? Paying fully in cash or CPF, you follow the same two-stage split as an HDB loan (10% at signing, 15% at keys) unless you are on the SDS.
Can I use a grant to reduce the cash I need? Grants are paid into your CPF OA, not as cash, so they reduce the CPF portion and the effective price — not the minimum cash slice a bank loan requires.
Related
- Loan-to-value (LTV) limits explained
- The real cost of buying an HDB flat
- Using CPF to buy a flat
- HDB loan vs bank loan
General information to help you budget, not financial advice. Confirm your exact figures with HDB, CPF and MAS before you commit.
Sources
- Sign Agreement for Lease (downpayment payable) — Housing & Development Board (as of November 2026)
- Booking of Flat (option fee) — Housing & Development Board (as of November 2026)
- The HDB Guide for Young Couples (Staggered Downpayment Scheme, Deferred Income Assessment) — HDB (MyNiceHome) (as of November 2026)
- Details on Deferred Income Assessment (Annex A) — Housing & Development Board (as of November 2026)
- Using your CPF to buy a home — Central Provident Fund Board (as of November 2026)
- Loan Tenure and Loan-to-Value Limits — Monetary Authority of Singapore (as of November 2026)